
Dhipaya Insurance is a state-linked Thai insurer known for cheap car insurance, especially if you don’t drive much. It also sells an O-A retirement visa health plan with THB3.5 million of hospital cover for people up to 80.
When you shop for car insurance in Thailand, Dhipaya’s prices stand out. They are lower than many rivals for similar cover, but its claims handling is stricter, and I’ve seen that first-hand in my own family.
Dhipaya has been selling insurance since 1951. Its big shareholders include Krung Thai Bank, the Government Savings Bank and PTT, so many Thais see it as a semi-government company.
Below I cover Dhipaya’s car insurance, its health and accident plans for foreigners, how claims work and what it all costs, so you can decide whether the savings are worth the stricter claims.
Disclaimer: Some links in this article go to our partners, and we may earn a commission if you use them. It costs you nothing extra, and we only recommend services we'd use ourselves. Read more in our Advertising Disclosure.
Contents
- Key Takeaways
- Dhipaya Insurance at a Glance
- What Is Dhipaya Insurance?
- Car Insurance
- How Much Does Dhipaya Insurance Car Insurance Cost?
- Health Insurance
- How to Buy and Contact Dhipaya Insurance
- Disadvantages
- Should I Get It?
- Alternatives
- Frequently Asked Questions
- Is Dhipaya Insurance the same company as Dhipaya Group Holdings (TIPH)?
- When was Dhipaya Insurance founded, and who owns it?
- Is Dhipaya Insurance regulated in Thailand?
- Does Dhipaya Insurance offer English-language customer service?
- Does Dhipaya have a health plan for the retirement visa?
- What is TIP Lady insurance?
- What can I do if I have an unresolved dispute with Dhipaya Insurance?
- Disclaimer
- Sources Cited
Key Takeaways
- Dhipaya is best known for affordable car insurance. Its low-mileage Type 1 plan, TIP Up to Mile, starts at THB4,900 a year.
- It sells compulsory cover plus Type 1, 2+, 3+ and 3, including a Type 1 plan for women drivers called TIP Lady.
- Claims can be strict, but Dhipaya pays when you follow the procedure.
- The TIP Long Stay VISA OA plan covers up to THB3.5 million a year in hospital for people up to 80, from THB27,000 a year.
- Its cheaper health and accident plans are affordable but have low limits.
- Many Thais see it as semi-government, because Krung Thai Bank, the Government Savings Bank and PTT are major shareholders.
- The call centre is 1736.
Dhipaya Insurance at a Glance
Dhipaya Insurance suits budget-minded drivers, especially those who don’t drive much, and retirees who need a low-cost O-A visa health plan.
Dhipaya Insurance
Thai car, health and accident insurer since 1951
- Car insurance
- Compulsory, Type 1, 2+, 3+ and 3
- Low-mileage Type 1
- TIP Up to Mile, from THB4,900 a year
- Type 3+ from
- THB5,399 a year
- O-A visa health plan
- THB3.5 million a year in hospital
- Visa plan price
- From THB27,000 a year
- Visa plan ages
- 14 days to 80
- Call centre
- 1736
- Founded
- 1951
Need health cover instead? Compare health insurance plans
Verified October 2026.
What Is Dhipaya Insurance?
Dhipaya Insurance is a Thai non-life insurer founded on 9 November 1951, whose major shareholders include Krung Thai Bank, the Government Savings Bank and PTT. The Ministry of Finance once owned most of it and handed its shares to those three state-linked companies.
According to AM Best, Dhipaya Insurance is one of the largest non-life insurers in Thailand.
Its main products are car insurance, personal accident insurance, fire insurance and marine insurance.
Some people call Dhipaya a semi-public company, because most of its shares sit with public organisations such as PTT (itself more than half owned by the Ministry of Finance), the Government Savings Bank and Krung Thai Bank. Since 2021, its shares have traded through a holding company, Dhipaya Group Holdings (TIPH), but your policy is still with Dhipaya Insurance.
Is Dhipaya Insurance Credible?
Dhipaya Insurance is credible. It has been in business for over seven decades, and with government-linked shareholders, it is expected to stay around for the foreseeable future.
Dhipaya can be strict when you make a claim, but it does pay as long as you follow every step of the procedure correctly.
Car Insurance
Dhipaya Insurance sells compulsory car insurance and every main voluntary type from Type 1 to Type 3, and its Type 3+ starts at THB5,399 a year. (Verified October 2026.)
Dhipaya’s car insurance range also includes Type 1 plans for low-mileage drivers and for women drivers:
| Plan | What it covers | Starting price |
| TIP Best Drive / TIP Premium (Type 1) | Full cover for your car and the other party, including theft, fire and flood | Quote only |
| TIP Up to Mile (Type 1) | Type 1 cover priced by how far you drive, with extra miles you can buy during the year | THB4,900 a year |
| TIP Lady (Type 1) | Type 1 for women drivers, with roadside help, up to THB1 million for surgery after an accident and cover for a handbag or belongings | Quote only |
| Type 3+ | Crashes with another vehicle, up to THB10 million for injuries you cause per accident, THB100,000 personal accident | THB5,399 a year |
Type 1 plans usually come in two or three versions. The main differences are the limits on third-party liability and medical cover.
Car Insurance Coverage
Even on its highest plan, Dhipaya’s car cover is much the same as other insurers’. Car insurance in Thailand is competitive and tightly regulated, so the cover for own damage, fire, flood and medical costs looks similar everywhere.
Partner Garages
Dhipaya has partner garages all over Thailand. Based on what I’ve seen, its network is on par with Viriyah Insurance and Bangkok Insurance, so you should find one near you wherever you live.
Car Insurance Claims
To report a Dhipaya car claim, call 1736 and press 1; accident and health claims go to 1736, then 2 and 1. (Verified October 2026.)
You can also manage policies in the TIP Insure app and send health and accident claims through the TIP Flash Claim app.
The claims process is Dhipaya’s biggest weakness. It has a reputation for being very strict about approving claims and trying hard not to pay.
My father-in-law once hit a parked motorcycle through his own carelessness in a private hospital car park. He called a Dhipaya representative to the scene.
The representative tried to argue that the motorcycle’s rider was also to blame, since he had parked in a restricted area (which a security guard had allowed).
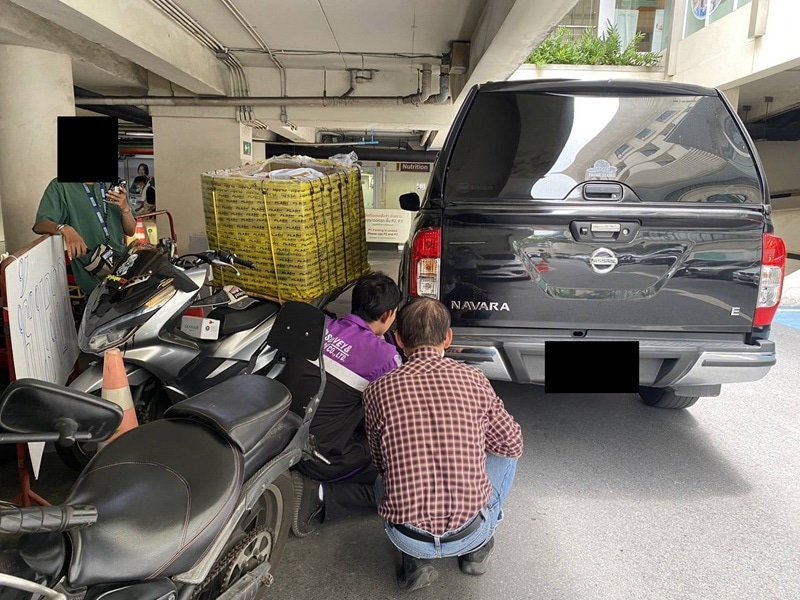
The representative did this so the company wouldn’t have to pay to fix the motorcycle. My father-in-law then had to go back and forth between the local police station and the hospital with the representative and the rider.
In the end, it was still my father-in-law’s fault and Dhipaya paid for everything, but everyone involved lost half a day.
Community Input: In a December 2024 r/Thailand thread on car insurance, one driver said they had used Dhipaya for 10 years and never had a problem. They speak Thai, so they couldn’t say how good its English support is.
Should I Buy Car Insurance from Dhipaya Insurance?
Dhipaya Insurance is a good option if price is your main concern and you pick its cheaper plans, such as Type 3+ or the low-mileage TIP Up to Mile. The company is credible, and its partner garages are easy to find.
If you drive less than 10,000 km a year, Dhipaya is even more interesting, since its plans can be at least 20% cheaper than other insurers.
Your claims may not go as smoothly as with Viriyah Insurance or Muang Thai Insurance, though. Fit a dashcam and take photos of everything.
How Much Does Dhipaya Insurance Car Insurance Cost?
Dhipaya’s Type 1 was the most expensive of the four in our CheckDi comparison, at THB18,750 a year, but it also had the highest personal accident and medical cover, at THB300,000 each. Its cheaper plans are where it wins on price: its Type 3+ cost THB4,900 a year, below the THB5,399 starting price on Dhipaya’s own website, and it had the cheapest Type 1 for a 2018 Honda City at THB5,900.
We ran live quotes on CheckDi for a 2023 Toyota Yaris Ativ 1.2 sedan registered in Bangkok and insured for THB350,000, with garage repair and no deductible. This is how the Type 1 plans compared:
Swipe sideways to see every plan →
| Type 1 quote | Chubb | Muang Thai | Viriyah | Dhipaya |
| Your car (crash) | THB350,000 | THB350,000 | THB350,000 | THB350,000 |
| Fire and theft | THB350,000 | THB350,000 | THB350,000 | THB350,000 |
| Injury or death of other people | THB500,000 per person | THB500,000 per person | THB1,000,000 per person | THB1,000,000 per person |
| Damage to other people’s property | THB5,000,000 | THB5,000,000 | THB5,000,000 | THB5,000,000 |
| Personal accident | THB200,000 | THB100,000 | THB200,000 | THB300,000 |
| Medical expenses | THB200,000 | THB100,000 | THB200,000 | THB300,000 |
| Bail bond | THB300,000 | THB300,000 | THB200,000 | THB300,000 |
| Deductible | THB0 | THB0 | THB0 | THB0 |
| Price per year | THB13,600 | THB14,501 | THB18,000 | THB18,750 |
Chubb was the cheapest of the four with the same THB5,000,000 cover for other people’s property. Viriyah and Dhipaya cost THB3,500 to THB4,250 more than Muang Thai, but pay twice as much for injuries to other people and more for personal accident and medical bills.
A deductible, the amount you pay yourself on each claim, brings the price down. AXA quoted THB10,700 for the same THB350,000 cover with a THB3,000 deductible. The cheapest Type 1 overall was THB9,100 from Indara, but that plan only covers your own car up to THB100,000.
For cheaper types of cover on the same car, these were the yearly prices across all insurers on CheckDi:
Swipe sideways to see every plan →
| Type of cover | Cheapest | Typical | Most expensive | Cheapest three insurers |
| Type 2+ | THB5,101 | THB6,699 | THB9,501 | Aioi, KPI, Thaivivat |
| Type 3+ | THB4,600 | THB6,000 | THB11,800 | Aioi, Muang Thai, Dhipaya |
| Type 3 | THB1,800 | THB2,301 | THB4,297 | Chubb, Indara, MSIG |
The value of your car changes the Type 1 price the most. For a 2018 Honda City insured for THB210,000, the cheapest Type 1 garage-repair quote was THB5,900, from Dhipaya.
If you rarely drive, Dhipaya’s TIP Up to Mile Type 1 starts at THB4,900 a year and lets you buy extra distance if you need it.
Your own price depends on your car’s model, age, value and province, so the quickest way to check is to run a quote. CheckDi is a licensed Thai insurance broker that shows plans from many insurers on one page, and its English-speaking team can help you buy and claim. Our CheckDi review explains how it works.
Health Insurance
Dhipaya’s main health plan for expats is TIP Long Stay VISA OA, which covers up to THB3.5 million a year in hospital for the O-A retirement visa and costs THB69,000 a year at ages 61 to 70 with no deductible. (Verified October 2026.)
Dhipaya also has cheaper health plans for Thais and expats, but they come with low limits.
TIP Long Stay VISA OA
TIP Long Stay VISA OA comes in two plans with the same THB3.5 million yearly limit. Plan 1 has no deductible, and Plan 2 is cheaper with a THB10,000 deductible per stay. (Verified October 2026.)
Swipe sideways to see every plan →
| Benefit | Plan 1 | Plan 2 |
| Hospital limit per year | THB3,500,000 | THB3,500,000 |
| Deductible per stay | None | THB10,000 |
| Room per night (up to 90 nights) | THB10,000 | THB10,000 |
| ICU per night (up to 15 nights) | THB20,000 | THB20,000 |
| General hospital costs per stay | THB150,000 | THB150,000 |
| Surgery per stay | THB250,000 | THB250,000 |
| Doctor visit in hospital, per day | THB2,000 | THB2,000 |
| Emergency accident care (within general costs) | THB50,000 | THB50,000 |
| Outpatient per visit (30 visits a year) | THB1,500 | THB1,500 |
| Accidental death or disability | THB100,000 | THB100,000 |
| Price per year, age 51 to 60 | THB55,000 | THB47,000 |
| Price per year, age 61 to 70 | THB69,000 | THB59,000 |
| Price per year, age 71 to 80 | THB90,000 | THB76,000 |
The THB3.5 million is a ceiling rather than what one stay will pay. Each part of the bill has its own cap, so a stay pays at most THB150,000 in hospital costs and THB250,000 for surgery, plus the room and doctor fees.
- Ages: 14 days to 80 years old, with cover continuing to 80.
- Pre-existing conditions: not covered if you hadn’t recovered before the policy started.
- Waiting periods: 30 days for any illness, and 120 days for tumours and cysts, hernias, cataracts, haemorrhoids, stones and a few other conditions.
- How to buy: fill in a proposal form and apply through a Dhipaya branch.
Dhipaya is on the Thai General Insurance Association’s list of insurers that can issue the O-A visa health insurance certificate.
Other Health Plans
Dhipaya’s TIP Deluxe Healthcare plan shows how low the limits on its cheaper plans can be: at ages 61 to 70, it pays up to THB100,000 a year in hospital, THB5,000 a night for the room and THB1,200 per outpatient visit. You can join from 15 to 70 and renew until 80. (Verified October 2026.)
Dhipaya also sells online plans through its TIPINSURE site, mostly in Thai. TIP Chill Chill starts at THB4,240 a year for ages 15 to 60 and pays up to THB50,000 per hospital stay, while TIPINSURE Yant starts at THB8,888 with up to THB500,000 a year. (Verified October 2026.)
Personal Accident Insurance
Dhipaya’s PA Triple Plus accident plan comes in seven levels with up to THB1.2 million of cover, worldwide, including motorbike accidents and assault, from a few hundred baht a year. (Verified October 2026.)
Other Insurance
Dhipaya also sells travel insurance and fire and property insurance. These help if you want one insurer for more than your car, though we haven’t reviewed them in the same depth. Our Thailand travel insurance guide shows how Dhipaya’s travel plans compare with dedicated travel insurers, and our guide to other types of insurance covers the rest.
How to Buy and Contact Dhipaya Insurance
You can buy most Dhipaya policies on its English-language website or in the TIP Insure app, which also handles claims and renewals. The call centre is 1736.
If you’d rather compare Dhipaya with other insurers first, a licensed insurance broker in Thailand can do that in one place. For a wider view, see our roundup of other insurance companies in Thailand.
If you can’t settle a claim or complaint with Dhipaya directly, Thailand’s Office of Insurance Commission (OIC) handles complaints and mediation for every licensed insurer.
Disadvantages
Dhipaya Insurance’s main drawbacks are strict claims handling and low limits on its health plans:
- Claims can be strict and slow, with a representative who may argue over who is at fault.
- TIP Long Stay VISA OA caps each stay at THB150,000 for hospital costs and THB250,000 for surgery, far below the THB3.5 million headline.
- Its cheaper health plans have very low limits, such as THB100,000 a year at ages 61 to 70 on TIP Deluxe Healthcare.
- None of its health plans cover pre-existing conditions.
- The visa plan is sold through branches with a paper form, and most online health plans are only described in Thai.
Should I Get It?
Dhipaya Insurance is a legitimate insurer whose car, health and accident plans tend to cost less than its competitors’. If you’re on a budget and want affordable cover from a reputable company, especially if you drive little, it’s a good option.
If you want generous cover, great customer support and smooth claims, look at the alternatives below. For a retirement visa, its Long Stay plan is a cheap way to meet the O-A rule, but the per-stay caps mean it won’t cover a big operation.
Alternatives
For car insurance, the other big Thai insurers are worth a quote:
- Bangkok Insurance: pricier than Dhipaya but known for easy claims. See our Bangkok Insurance review.
- Viriyah Insurance: a big car insurer with a smoother claims reputation. See our Viriyah Insurance review.
- Muang Thai Insurance: another major insurer with a good claims record. See our Muang Thai Insurance review.
Our guide to car insurance in Thailand explains the policy types and how to compare quotes.
For health insurance, these plans give you more cover:
- AXA EasyCare Visa: a low-cost Thai plan that comes with the O-A and O-X visa certificate. See our AXA EasyCare Visa review.
- Luma Health: a Thai health plan built for expats and priced in baht. See our Luma Health review.
- Cigna Healthcare: international cover with no upper age limit to join. See our Cigna Healthcare Thailand review.
To compare health plans side by side, use our expat health insurance comparison.
Frequently Asked Questions
Dhipaya Insurance sells car, health and accident cover to foreigners through its website, its app, its branches and brokers.
Is Dhipaya Insurance the same company as Dhipaya Group Holdings (TIPH)?
No, but they’re closely linked. Dhipaya Insurance is the insurer that issues your policy, and TIPH is the listed parent company created in 2021.
When was Dhipaya Insurance founded, and who owns it?
Dhipaya Insurance was founded on 9 November 1951 by Field Marshal Sarit Dhanarajata. Its major shareholders have included Krung Thai Bank, the Government Savings Bank and PTT, which is why many Thais consider it a semi-government company.
Is Dhipaya Insurance regulated in Thailand?
Yes. Like every non-life insurer in Thailand, Dhipaya Insurance is licensed and supervised by the Office of Insurance Commission (OIC).
Does Dhipaya Insurance offer English-language customer service?
Dhipaya’s website runs in English at dhipaya.co.th/en, and the call centre is 1736. Confirm English support for your product when you buy, since it can vary by department.
Does Dhipaya have a health plan for the retirement visa?
Yes. TIP Long Stay VISA OA covers up to THB3.5 million a year in hospital for the O-A visa, for people aged 14 days to 80, from THB27,000 a year.
What is TIP Lady insurance?
TIP Lady is Dhipaya’s Type 1 car insurance for women drivers. It adds roadside help, up to THB1 million for surgery after an accident and cover for a handbag or personal belongings.
What can I do if I have an unresolved dispute with Dhipaya Insurance?
You can take an unresolved complaint to Thailand’s Office of Insurance Commission (OIC), which handles complaints and mediation for every licensed insurer in the country.
Disclaimer
*While we try our best to provide you with up-to-date and accurate information, the volatile nature of the insurance business means some of the information above may be subject to change. Please use it only as a guideline, and if you have any doubts, it’s best to check directly with Dhipaya Insurance or an insurance broker.
We are not an insurance broker and can’t offer individualized advice. We can only connect you with people who we would consult in your situation, and who we found to be professional, knowledgeable, and ethical in their dealings with clients.
These providers sometimes provide us with financial incentive to refer new clients to them. This happens at no cost to you and helps us cover some of the expenses of running this website.
Please be aware that while we do our best to select the most suitable providers, we’re unable to provide any guarantees or accept any liability resulting from your interactions and transactions with our partners.
Sources Cited
- Dhipaya Insurance, company profile: founding date and founder, shareholder history, 1996 SET listing, 2021 move to Dhipaya Group Holdings (TIPH).
- Dhipaya Insurance, motor insurance, TIP Up to Mile, TIP Lady and Type 3+: car plans, cover and starting prices.
- Dhipaya Insurance, TIP Long Stay VISA OA: benefits, deductible, premium table, ages, waiting periods and how to apply.
- Dhipaya Insurance, TIP Deluxe Healthcare: benefits by age band.
- TIPINSURE (Dhipaya Insurance), online health plans and PA Triple Plus: online plan prices and limits, accident cover.
- Dhipaya Insurance, automobile claim service and applications: 1736 claim lines, TIP Insure and TIP Flash Claim apps.
- AM Best press release: market position.
- Thai General Insurance Association, O-A participating companies: insurers that can issue the O-A health insurance certificate.
- Reddit r/Thailand, car insurance recommendations thread (December 2024): Community Input.
- CheckDi live car and motorbike insurance quotes, pulled 6 and 14 October 2026: 2023 Toyota Yaris Ativ 1.2 and 2018 Honda City 1.5, registered in Bangkok; 2024 Honda Click 125i and Honda CB500F

 Deutsch:
 Français:
 Español: