Choosing the right insurance broker in Thailand takes knowing the difference between local and international policies, verifying OIC licensing, and asking the right questions. This guide walks you through all of it.
Finding the right insurance broker in Thailand can be challenging when you’re trying to protect yourself and your family abroad.
You know you need insurance coverage, but you also need to know that the broker is recommending what’s best for you and your loved ones. You also need to know which brokers are licensed and legitimate. Lastly, you might want to look at the pros and cons of local Thai policies and international coverage.
These concerns are the same many expats in Thailand face every day. After all, the insurance industry here runs quite differently than what you’re used to back home.
This guide cuts through the confusion by showing you exactly how to identify trustworthy, properly licensed brokers, understand the real differences between local and international coverage options, and avoid commission-driven recommendations that don’t serve your interests.
You’ll also find out which brokers specialize in expat needs, how to verify credentials, and what questions to ask to ensure you’re getting unbiased advice rather than just a sales pitch.
Disclaimer: Some links in this article go to our partners, and we may earn a commission if you use them. It costs you nothing extra, and we only recommend services we'd use ourselves. Read more in our Advertising Disclosure.
Contents
- Key Takeaways
- What You Must Know Before Picking an Insurance Broker
- International Policies and Local Policies
- International Insurance Brokers
- Local Thailand Insurance Brokers
- Freelance Insurance Brokers
- Brokerage Companies by Language
- Questions to Ask Your Insurance Broker
- Does the Insurance Cover Your Pre-Existing Conditions?
- Can You Give Me a Detailed List of Exclusions and Waiting Periods for the Recommended Plan?
- What Are the Rules About “Choice of Hospital” and “Reasonable Medical Expenses”
- How Long Has This Plan Been on the Market?
- Is There a Group Discount to Insure My Entire Family?
- Can You Go to Any Hospital in Thailand, Without Restriction?
- Additional Information You Should Tell Your Broker
- Pros of Using an Insurance Broker
- Things to Clarify Upfront
- How to Complain About a Broker or Agent to the OIC
- Insurance Broker Alternatives
- How to Check a Broker's Licence on the OIC Website
- How to Vet a Licensed Broker
- Frequently Asked Questions
- Do I have to pay an insurance broker in Thailand?
- Is it better to buy through a broker or directly from the insurer?
- How do I check that a broker is properly licensed?
- Can a broker help me meet Thailand's visa insurance requirements?
- Is a broker liable if my claim gets denied?
- Can I switch brokers after I have bought a policy?
- Do local and international brokers offer the same plans?
- What should I tell a broker before they recommend a plan?
- What is the difference between an insurance agent and a broker in Thailand?
- Does a broker's licence expire?
- Who do I complain to if a broker misled me?
- Can my health insurer add a co-payment when I renew?
- Sources Cited
- Which Insurance Broker Should You Use in Thailand?
Key Takeaways
- Insurance brokers in Thailand are categorized as Thai-owned local, expat-owned local, or international, each with different strengths.
- All brokers in Thailand must hold a license from the Office of Insurance Commission (OIC); always verify credentials before signing anything.
- Local brokers are best for car insurance and Thai plans; international brokers have more choices for offshore health coverage.
- You pay nothing extra when using a broker; they earn a 10 to 18 percent commission directly from the insurance company.
- Always ask your broker about pre-existing condition coverage, exclusions, waiting periods, and hospital network restrictions upfront.
- For international health insurance, International Citizen Insurance is a solid choice; for local plans, CheckDi is well-regarded.
- Some brokers offer services in German, French, and Chinese; contact your embassy if you prefer to work in your native language.
- Verify credentials, read reviews from other expats, and understand broker liability limits before committing to any plan.
What You Must Know Before Picking an Insurance Broker
We’ll get to the list of brokers in a minute. First I want to give you at least a little bit of background, so you understand some basic things about insurance brokers in Thailand and can put all of this into some context.
Life Insurance or Everything Else
Brokers advise you on two different types of products: Life insurance and non-life insurance. If you’re a keen follower of formal logic, I’ll have to disappoint in that non-life insurance doesn’t actually entail all things that are not life insurance. So let’s just rephrase that to “brokers advise you either on life insurance or on all other insurance products, including but not limited to health insurance”. There, my lawyer would be proud. As a bonus – and here you may need to constrain your excitement – here is a list of all available insurance products in Thailand that this may involve. More frequently than not, brokers offer both (which may or may not be exactly in line with government regulations).
Life Insurance
Life insurance is the only insurance that falls within the life insurance type. Brokerage companies in Thailand do not have many life insurance options for expats.
Many of them do not offer it at all since it’s pretty difficult for expats to buy life insurance in Thailand. But it’s still possible if you buy it from an international life insurance broker.
Non-Life Insurance
In Thailand, every type of insurance that isn’t life insurance is considered non-life insurance products, including health insurance, car insurance, property insurance, travel insurance, and so on.
Although there are many brokerage companies in Thailand that offer non-life insurance only, they may have different specializations.
For example, one brokerage company might only focus on health insurance while another may specialize in commercial insurance for business. So know their specialization before contacting them.
Usually, local brokers in Thailand focus on car insurance because it’s a big market there. For health insurance, international brokers often know more about plans for expats.
International Policies and Local Policies
There are both international and local insurance policies available for expats in Thailand.
To purchase local plans, you must buy them from local brokers.
Conversely, international policies should be obtained from international providers. Although some local brokers may offer international policies, the options are limited.
For example, a local brokerage company, CHECKDI, has a single international health insurance plan, while International Citizen Insurance, an international broker, has all popular international plans.
So if you are looking for an offshore health insurance plan, it’s best to contact an international brokerage company instead. In addition, some brokerage companies may not provide insurance plans offered by Thai banks.
Brokerage License
All insurance brokers and brokerage companies in Thailand must obtain a brokerage license from the Office of Insurance Commission (OIC), per OIC regulations. This is for your protection as a consumer.

Foreigners can only hold a broker licence if they meet the OIC’s residence and training requirements, and many expat-run brokerages operate through a licensed company, so ask to see the licence.
The legal way to do so is that they must be working for some insurance brokerage companies and use the license from the brokerage company to sell insurance.
However, there are also some people who essentially just have their Thai spouse signed up as an insurance agent of various insurance companies.
Then, after they do the selling, they ask their Thai spouse to sign the documents to issue the insurance which, of course, isn’t entirely legal.
Insurance Agent vs Insurance Broker Under Thai Law
Many people use “agent” and “broker” as if they mean the same thing. Thai law treats them as two different licences, and the difference decides whose interests the person works for. (Verified October 2026.)
| Insurance agent | Insurance broker | |
|---|---|---|
| Who they work with | One insurance company that appoints them | Any company; they arrange contracts between you and an insurer |
| Legal definition | A person delegated by the company to solicit people to buy its policies | A person who, for commission, indicates opportunities or arranges for people to enter into insurance contracts with a company |
| Who can hold the licence | Individuals only | Individuals or companies |
| Licence shows | The insurer they represent | Their own name, or the brokerage company |
| Can hold the other licence too? | No. An agent cannot also be a broker, and a broker cannot be an agent or an employee of an insurance company. | |
In practice, an agent can only show you the products of the one insurer they are appointed to. A broker can compare several insurers, which is why the rest of this guide focuses on brokers.
A brokerage company must also put a licensed individual in charge of advising and arranging contracts, and the company is jointly responsible for damage caused by the person it assigns. That gives you a company to hold to account, not just an individual.
Types of Insurance Brokerage Companies
There are three main types of insurance companies in Thailand:
- A local brokerage company owned by Thais
- A local brokerage company owned by expats
- An international brokerage company
Here are their main differences:
Local Brokerage Company Owned by Thais
A local brokerage company owned by Thais mainly provides local insurance plans. Many of them are established brokerage companies in Thailand before they’ve expanded their services to expats.
They have a good understanding of local plans, especially car insurance, but have limited options on international plans. These brokerage companies are known to employ Filipino staff to handle expat customers exclusively.
CHECKDI is a good example of a brokerage company of this type.
Local Brokerage Company Owned by Expats
It’s possible for expats to run their own brokerage companies in Thailand if they have legally registered a company in Thailand and fulfilled all requirements of the OIC.
Since this type of company is owned by expats, you might be able to speak to a broker who comes from the same country and speaks the same language as you do.
This type of brokerage company can offer both local and international plans.
International Brokerage Company
Some international brokerage companies may not have offices in Thailand, but you can still buy insurance from them.
What’s good about international brokerage companies is that they have lots of international plans available. You can even keep using their services even after you’ve moved out of Thailand.
However, they don’t provide any local plans at all.
So if you want to buy an international health insurance plan, get in touch with them.
International Citizen Insurance is a good example of a brokerage company of this type.
Do You Have to Pay for an Insurance Broker’s Services?
You won’t need to pay when using both local brokers and international brokers. Instead, they make money in the form of commissions from insurance companies.
Brokerage companies get an average of 10 to 18 percent commission of your premium, which is the industry standard.
International Insurance Brokers
If you want to get health insurance, your options won’t be limited to only brokerage companies in Thailand.
You can contact the following international brokers for international plans.
Carsten Creutzburg
I’ve known Carsten for many years. He’s a German insurance broker who worked in German social security before running his own brokerage firm. Carsten lived in China for many years before moving to Thailand.
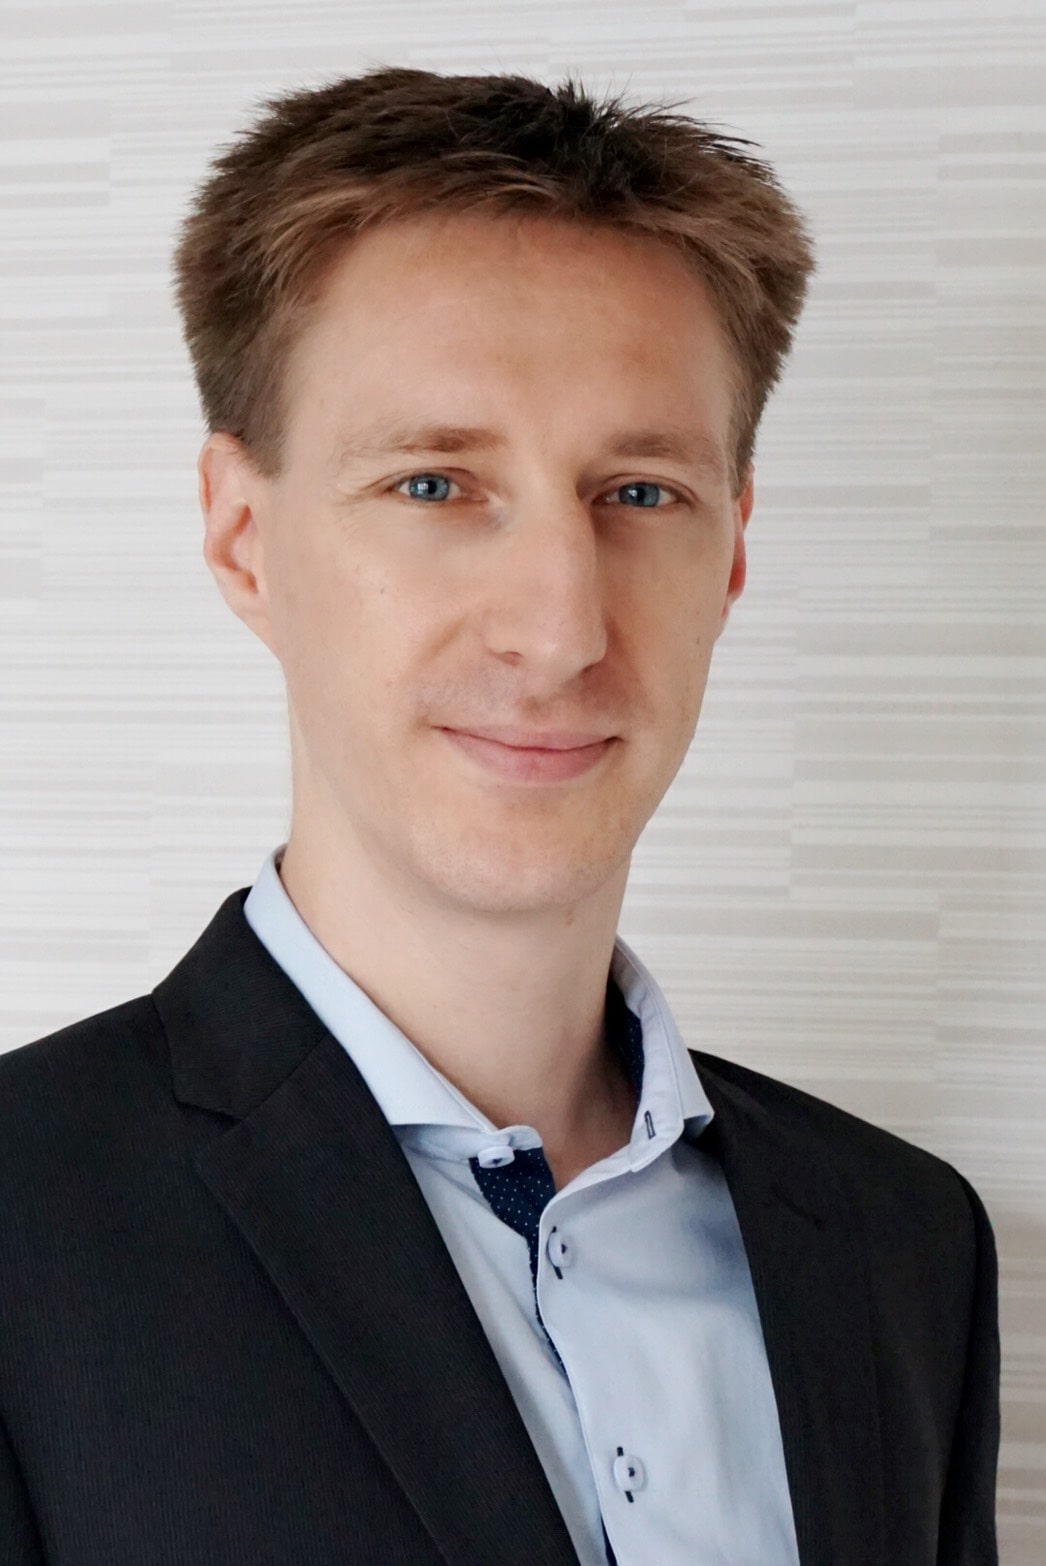
While he doesn’t know much about local insurance plans in Thailand, he’s very knowledgeable when it comes to international insurance. Every time I ask him about any insurance plans, he gives me a detailed answer as if he’s writing a report.
So, if you need help finding a good plan as an expat in Thailand, I highly recommend him since he also lives here.
However, due to his German sense of humor, some people may find him a little rude. But trust me, he will give you an honest answer. Also, he normally recommends some smaller insurance companies that offer good value for money.
It’s also good to know that Carsten prefers to communicate over email. And he works alone, so it might take some time for him to reply to you. If you haven’t heard from him in 2-3 days, I recommend sending him a follow-up email.
You can use this form to get in touch with him or read our review here.
International Citizen Insurance
International Citizen Insurance is an American international brokerage company.
They partner with leading international insurance companies including Cigna, GeoBlue, International Medical Group (IMG), and Now Health to provide international insurance to expats worldwide.
International Citizens Insurance is a good choice for obtaining international health insurance. They have a team of licensed agents who will assist you throughout the process of finding and purchasing coverage, as well as during the life of the plan.
In fact, we have been referring our readers to them for many years, and they are satisfied with their service.
You can request a quote for free personalized health insurance options for your move abroad or to compare coverage with your current plan.
Some expats who have bought insurance through International Citizen Insurance share their experiences below:
I required insurance for living abroad and International Citizens Insurance was prompt and professional in helping me get what I was looking for. They are quick, easy to communicate with and helpful. Thanks!
– Lauren T
Very good service- Brennan was incredibly patient (I can’t even count how many times I emailed him!) and quickly answered any questions that I had.
He was very knowledgeable as well and quickly won my trust as an expert on the policies to choose from. Highly recommended.
Kathleen H.
AOC Insurance Broker
AOC Insurance Broker is another international insurance brokerage company providing a wide range of international health insurance plans.
Their head office is in France and they have a branch office in Hong Kong.
Now Compare
Now Compare is an international health insurance comparison platform where you can compare a range of international health insurance plans in one place.
However, you can only compare the coverage amount of premiums, which isn’t enough information when buying health insurance.
If you need more information, you need to contact them.
Local Thailand Insurance Brokers
Many insurance brokerage agents in Thailand can speak English fluently. These companies are either run by expats or they hire expats to handle foreign clients.
CheckDi
CheckDi is a well-known insurance brokerage company popular among locals in Thailand for car insurance.
They have expanded their products and are now providing insurance policies to everyone who is living or planning to visit or live in Thailand.
One of the best things about CheckDi is their website. You can read and compare all insurance plans they provide in a single place.
When you find a plan that you like, you can apply directly or contact their brokers to get more information.
Some expats who have bought insurance from CheckDi share their experiences below:
I called many insurance companies and brokers during my search for a health insurance provider. I found that CheckDi gave me very good insight, especially my agent (her name is Mady) who was very helpful and knowledgeable.
Info I got helped me make a better decision amidst the myriads of choices out there. That’s the beauty of going through a broker, esp. when you don’t know what provider to pick. Since brokers offer plans from many providers, they will give you info on different providers out there without preference. At least it was like that for my experience.
Patra Jankovic
CheckDi has helped me sort out my insurance when I first arrived in Thailand. I just applied online and sent them some requirements and they did everything for me from then on. It was quick and easy.
They also help out with claims and other problems we may have and I think that’s the best part about buying through them. They’ve been really helpful.
Emma Vanloot
AA Insure
If you’ve browsed through local forums before, you might have seen the name AA Insurance Brokers.
They are an insurance brokerage company in Thailand with offices in popular expat destinations, including Pattaya, Huahin, and Phuket.
BSI Insurance Broker Limited
BSI Insurance Broker Limited is a Thai insurance brokerage company that primarily focuses on health insurance for expats who are living in Thailand. They offer a wide range of local insurance plans including Luma, Axa, Thaivivat, and Bangkok Insurance.
Roojai
Roojai started as an online insurance broker in 2016. It now operates as Roojai Insurance PCL, a licensed insurance company, after acquiring FWD General Insurance in 2023, so today it is an insurer rather than a broker.
Car insurance is still its best-known product.
Additionally, you can find other non-life insurance products on their website, although they are limited at the moment.
InsurExcellence
InsurExcellence is a local insurance brokerage company that focuses on commercial insurance for businesses.
Trafalgar International
Trafalgar International is another local brokerage company that specializes in commercial insurance.
They also still provide personal health insurance, property insurance, and motor insurance.
Marsh
Marsh is an international brokerage company with a Thai branch. They specialize in commercial insurance and tailor-made insurance for business risk management.
Freelance Insurance Brokers
In Thailand, there are a lot of freelance brokers. The OIC requires these freelancers to get a license before they can sell insurance.
Many Thai freelance brokers work for AIA. They usually sell life insurance, and sometimes health insurance is included too.
A special thing about Thai freelance brokers is that they might visit you in the hospital with fruits or flowers if you’re admitted.
There are also expat freelance brokers who sell international plans. You can find many of them online.
Here’s what to keep in mind when choosing a freelance broker. Not all are experts. Some do it as a side job and might not know every detail about the insurance plans.
Brokerage Companies by Language
In addition to English, some companies are able to provide services in German, French, Spanish, and other languages.
Please note that the information below was based on research and recommendations from embassy websites, our friends, and readers.
If you prefer an insurance brokerage company that speaks your language, you can contact your country’s embassy or the chamber of commerce to get a recommendation.
German
There are a good number of insurance brokerage companies in Thailand that offer services in German. Many of them are run by German expats.
BSI Insurance Broker Limited
BSI Insurance Broker Limited always has a German-speaking team for their German clients.
AA Insurance Brokers
Similar to BSI Insurance Broker Limited, AA Insurance Brokers also always have a German-speaking team on board.
Global Insurance
Global Insurance is an insurance brokerage company based in Pattaya. The company is managed by Rainer Heizmann who speaks German, French, and English.

Global Solidor Enterprise
Global Solidor Enterprise provides a range of non-life insurance products, including health insurance, personal accident, corporate insurance, and even marine insurance. In addition to insurance, they also offer legal and real estate services.
French
AOC Insurance Broker
AOC Insurance Broker also has a team that can support French-speaking clients. However, note that they only offer international plans.
Chinese
KWI Insurance
A lot of Chinese-speaking insurers in Thailand, including KWI Insurance (an insurance company rather than a broker), cater towards Chinese corporations that conduct business in Thailand.
However, some do offer motor insurance, personal accident insurance, and property insurance for individuals.
Questions to Ask Your Insurance Broker
There’s a recommended set of questions that you should ask a broker.
The purpose of asking this question isn’t to test their knowledge but to tell them relevant information about your needs, so that they can recommend a plan that’s most suitable for you.
In case you do not understand any of the insurance terms in this section, please check out our health insurance in Thailand article for reference.
Does the Insurance Cover Your Pre-Existing Conditions?
Pre-existing conditions are the main exclusion of health insurance plans. If you have one, it’s better to tell your broker right away.
If you don’t disclose it and the insurance company finds out about it later, then it’s highly likely that they won’t pay it when you make a claim.
However, if you tell a broker in advance, they might be able to find you a plan that covers your pre-existing conditions.
Can You Give Me a Detailed List of Exclusions and Waiting Periods for the Recommended Plan?
All insurance plans have a long list of exclusions and waiting periods for specific procedures.
These are two of the most important things you must know before buying any insurance product.
Asking this question would save you and your broker a lot of time.
Many people have been dealing with brokers and may have been asking each other questions back and forth about a certain plan. However, what they may not realize is that a particular plan may have a waiting period of one month.
When they learn about it, they may decide to switch to another plan, and ask brokers yet another series of questions.
What Are the Rules About “Choice of Hospital” and “Reasonable Medical Expenses”
You may encounter these terms on certain insurance plans.
Different insurance plans may have different definitions for these terms, so it’s better to have a clear understanding of what you will get before purchasing any plan.
How Long Has This Plan Been on the Market?
Ideally, the plan should be in the market for more than five years. This indicates that the plan has credibility.
Is There a Group Discount to Insure My Entire Family?
Some insurance providers offer a group discount for family plans. It can range from 10 percent to more than 20 percent.
Read our family insurance in Thailand article for more information.
Can You Go to Any Hospital in Thailand, Without Restriction?
Some insurance plans may require you to go to certain hospitals within their network only.
If you go to other hospitals outside of their network, they may require quotes before approving your claim.
Otherwise, you might not be able to make a claim at all.
Additional Information You Should Tell Your Broker
In addition to asking the above questions, you should inform your broker the following additional information about yourself:
- budget per month/year
- general requirements
- general travel plans
- countries you spend a lot of time in
- countries where you plan to move in the future
- how long you wish to stay insured
This information will help your broker come up with the plan that’s most suitable to your needs.
Pros of Using an Insurance Broker
Working with an insurance broker will benefit you in many ways. Here are some of the more important ones:
- Compare plans from a single source: Insurance brokers offer a range of insurance products, which means you can get in touch with one agent and compare different plans from multiple insurance companies at once. This saves time and effort compared to contacting each insurance company individually.
- Comprehensive help: When you purchase insurance from a broker, you get extensive additional support throughout the entire process. Beyond providing expert advice on the most suitable plan for your needs, they can assist you at every step from application to making claims. Many brokers can recommend top hospitals, help fill out insurance forms by asking important health questions, and leverage their relationships with insurance companies to make claims that might otherwise be deemed exclusions. Some brokers will even handle the entire claims process and coordinate with insurance companies on your behalf.
- Same price with added value: Even with all the support and convenience brokers provide, you won’t pay anything extra for their services. The price you pay for an insurance plan is identical to buying directly from the insurance company. To keep you as a customer, brokers provide additional support and personalized service as an incentive for choosing them over direct purchase.
- Brokers go above and beyond: If you’re hospitalized, some brokers may even visit you at the hospital and buy you flowers and fruit baskets. This is not uncommon practice; they do it when you buy life insurance from them.
These benefits make brokers valuable for you if you’re unfamiliar with Thailand’s insurance industry. You’ll also appreciate having a knowledgeable insider to guide you through the process.
Things to Clarify Upfront
While insurance brokers can provide valuable help, there are several things you should consider when working with brokers in Thailand. Knowing these factors will help you make better choices.
- Commissions: Brokers earn 10 to 18 percent commissions from insurance companies, which is industry standard. But it can create conflicts of interest. Some brokers may recommend plans that offer higher commissions rather than what’s truly best for your needs.
- Limited liability: Most brokers aren’t liable for coverage gaps, claim denials, or policy misunderstandings. If your broker fails to explain important exclusions or provides incorrect information about coverage, you’ll have to handle the outcome.
- Regulatory gray areas: Some expat brokers operate in legal gray areas regarding proper licensing and compliance. While they may work “under” a licensed company, the actual oversight and accountability can be unclear, especially for freelance brokers who may not know the insurance plan in detail.
- Language and technical barriers: Despite many brokers speaking English, some insurance terms can be poorly translated or misunderstood. This is true when dealing with policy exclusions, waiting periods, and claim procedures where precise language matters.
- Claim processing: Having an additional broker layer between you and the insurance company can sometimes delay claim processing. And some brokers may respond more slowly than others during medical emergencies.
- Market limitations: Thailand’s expat insurance market has fewer options compared to your home country, and brokers can only work with companies that operate here. This means you might miss out on better coverage or pricing elsewhere.
Despite these limitations, if you find the right broker, it makes navigating Thailand’s insurance landscape much easier. The key is choosing carefully, understanding these potential drawbacks, and maintaining realistic expectations about what brokers can and cannot do for you.
You can also read reviews about the broker’s services or ask for recommendations from other expats. Alternatively, you can ask for our personal recommendation.
How to Complain About a Broker or Agent to the OIC
If a broker misled you about the terms, hid something that cost you money, or sold you a policy without a valid licence, you can take the case to the OIC. Filing is free. (Verified October 2026.)
- Phone: the OIC hotline is 1186. It covers general questions about insurance as well as complaints, so it is the easiest first step if you are unsure how to proceed.
- Online: the OIC complaint portal at complaintportal.oic.or.th has a separate category for complaints about life and non-life agents and brokers, including misleading someone about policy terms and hiding information that causes loss. The portal is in Thai and signs you in with ThaID, the Thai government digital ID, then asks you to register through the OIC’s LINE account. If you do not have ThaID, call 1186 and ask how to file.
Before you file, collect the policy schedule, the emails or chat messages with the broker, your payment receipts and any quote you were given. A complaint with documents attached moves faster than one without.
If the problem is a rejected claim rather than the broker’s conduct, start with the insurer’s own appeal route. Our guide to disputing a rejected health insurance claim in Thailand walks through it.
Insurance Broker Alternatives
If you don’t want to buy insurance through a brokerage company, you have an option to buy it directly from insurance companies.
You can contact them through their websites and apply online.
You may even find freelance insurance brokers there. Freelance agents are tied to one insurer. An independent broker needs their own OIC broker licence or must work under a licensed brokerage company.
In Thailand, many banks also sell insurance.
Previously, these banks provided only life insurance. Now they have expanded their products.
For example, Kasikorn Bank now provides various types of non-life insurance, including health insurance, property insurance, personal accident insurance, and even motor insurance.
As mentioned earlier, you get the same product at the same price no matter if you buy insurance through a broker or an insurance company. The application procedure is also similar.
Ultimately, it all comes down to who you can trust and feel comfortable talking to.
How to Check a Broker’s Licence on the OIC Website
The Office of Insurance Commission (OIC) runs a public register of licensed agents and brokers. You can search it yourself in a couple of minutes, without asking the broker for anything. (Verified October 2026.)
- Open the OIC licence check page. It sits in the OIC e-services at oiceservice.oic.or.th. The page is in Thai only, so use your browser’s translate function.
- Pick the right list. The menu has separate lists for individual agents and brokers with a licence, those whose licence was revoked, and corporate brokers (companies). For a brokerage firm, use the corporate broker list. For a person, use the agent and broker list.
- Search by name or licence number. For individuals the form accepts first name, surname, licence number or Thai ID number, and can filter by insurance company or by life or non-life broker. Names are matched in Thai, so ask the broker for the Thai registered name and licence number.
- Read the result. The table shows the name, company, licence number, licence type, issue date, expiry date and status. Check that the type matches what they sell (life or non-life) and that the licence has not expired.
- Check the revoked list too. A person who does not appear as licensed may appear as revoked. Either result is a reason to stop.
Licences do not last forever. A new agent or broker licence is valid for one year, and after two consecutive renewals the next one runs for five years. An expiry date in the past means the person cannot legally sell to you right now.
The OIC page carries its own disclaimer that the data is general public information and cannot be used as legal evidence. Treat it as a quick check, and keep a screenshot of the result with your policy papers.
How to Vet a Licensed Broker
Before you act on any broker’s recommendation, run a few quick checks:
- Ask for the broker’s OIC license reference and the company name they are registered under with the Office of Insurance Commission.
- Confirm the brokerage is a legally registered company, especially if you are dealing with a freelance broker working under a firm’s license.
- Ask how long the plan they are recommending has been on the market, and get the exclusions and waiting periods in writing before you sign.
- If the plan is meant to satisfy a visa requirement, confirm it meets the current rules. Some visas carry mandatory minimum coverage; see our guide to mandatory health insurance rules for retirees.
- Compare the recommendation against the main insurance companies in Thailand so you judge the plan on its own merits, not just the pitch.
Frequently Asked Questions
Do I have to pay an insurance broker in Thailand?
No. Brokers earn a commission from the insurance company, typically up to 18 percent of the premium for non-life policies under OIC rules, so the price you pay for the plan is the same whether you buy through a broker or direct.
Is it better to buy through a broker or directly from the insurer?
Buying direct works if you already know which plan you want. A broker helps when you want to compare multiple insurers at once, get help with the application, or have someone to call when a claim gets complicated. Neither option changes the premium you pay.
How do I check that a broker is properly licensed?
Ask the broker or brokerage for their OIC license reference and the name they are registered under with the Office of Insurance Commission. Brokers can be licensed as individuals or as corporate entities, and dual licensing as both an agent and a broker is not allowed.
Can a broker help me meet Thailand’s visa insurance requirements?
Yes. A broker can confirm whether a specific plan satisfies the insurance requirements tied to certain visa categories, such as some retirement visa rules. Requirements vary by visa type, so confirm the current rules for your visa before buying.
Is a broker liable if my claim gets denied?
Generally no. The contract is between you and the insurance company, so a broker is not usually liable for coverage gaps or claim denials. Ask the broker to explain exclusions and waiting periods in writing before you sign.
Can I switch brokers after I have bought a policy?
In most cases yes. You can work with a different broker or deal with the insurer directly for service on an existing policy, since the broker relationship is separate from the insurance contract. Check with the insurer if you are unsure how servicing works for your plan.
Do local and international brokers offer the same plans?
No. Local brokers mainly sell Thai-market plans and are strongest on car insurance and domestic health cover, while international brokers focus on global health plans you can usually keep after leaving Thailand. Some local brokers offer a few international options, but the selection is narrower.
What should I tell a broker before they recommend a plan?
Share your budget, any pre-existing conditions, how long you plan to stay in Thailand, which other countries you spend time in, and whether you need family coverage. This lets the broker narrow down plans instead of giving a generic recommendation.
What is the difference between an insurance agent and a broker in Thailand?
An agent is appointed by one insurance company and sells only that company’s policies. A broker arranges contracts between you and insurers for a commission and can compare several companies. Thai law gives them separate licences, and one person cannot hold both.
Does a broker’s licence expire?
Yes. Agent and broker licences are valid for one year and must be renewed with OIC training. After two consecutive renewals, the next licence is valid for five years. Check the expiry date in the OIC register before you pay a premium.
Who do I complain to if a broker misled me?
Complain to the Office of Insurance Commission. Call the hotline on 1186 or use the OIC complaint portal, which has a category for agents and brokers. Filing is free. Keep your policy documents and messages with the broker as evidence.
Can my health insurer add a co-payment when I renew?
Possibly. OIC guidance issued in 2025 allows an insurer to apply co-payment at renewal, but only if you meet its claims criteria in the previous year. The co-payment can be up to 30 percent of treatment costs, and the combined co-payment is capped at 50 percent. Ask your broker how a plan handles renewal before you buy. (Verified October 2026.)
Sources Cited
- Office of Insurance Commission, oic.or.th: licensing and regulation of insurance brokers in Thailand.
- CheckDi: local insurance comparison and brokerage (partner).
- International Citizen Insurance: international health insurance comparison (partner).
- OIC e-services: licence check for agents and brokers: public register of licensed and revoked agents and brokers, and corporate brokers.
- Non-life Insurance Act B.E. 2535 (1992), OIC unofficial translation: definitions of agent and broker, licence validity, and the rule that one person cannot hold both licences.
- Non-life Insurance Act (No. 4) B.E. 2562 (2019), OIC translation: broker company must assign licensed individuals and is jointly liable for them.
- OIC complaint portal (PPMS): free complaint filing, including complaints about agents and brokers, and the 1186 hotline.
- OIC PR News 10/2568 on health insurance co-payment: co-payment at renewal, 30 percent and 50 percent limits.
Which Insurance Broker Should You Use in Thailand?
We hope that this article answers most of your questions about brokerage insurance companies in Thailand.
Our quick picks:
- If you need international health insurance, contact Carsten Creutzburg.
- For local insurance, use CheckDi.
In case there’s anything we might have missed in the article, please feel free to let us know.

 Deutsch:
 Français:
 Español: